We Help Businesses Make Sense of Revenue They Haven't Earned Yet
Deferred revenue used to be a footnote. Now it shapes how your business is measured,
trusted, and valued.
Once upon a time, businesses recorded money when it arrived and asked questions later.
Today, accounting standards demand something more deliberate — a careful mapping of when
revenue is truly earned, not merely received. That gap between receiving cash and
recognizing it is where financial misstatements quietly take root. We exist to close
that gap, walking you through the planning frameworks, schedule structures, and
compliance considerations that turn deferred revenue from a liability into a
well-managed asset on your books.
Standards-Grounded Planning Approach
Every recommendation we make is anchored in current Canadian and IFRS revenue recognition standards, not improvised workarounds.
Structured Schedules That Actually Hold Up
We build recognition schedules designed to survive an audit, a board review, or a due diligence process without revision.
A Collaborative, Not Transactional, Relationship
We treat your finance team as partners, not recipients — working alongside your people, not around them.
Long-Horizon Thinking for Complex Revenue Streams
Subscription models, multi-year contracts, and bundled arrangements each require their own planning logic — we bring all of it.
What We Stand For
Four principles that shape every engagement, every schedule, and every recommendation we
make.
Precision Over Speed
A recognition schedule built quickly and revised repeatedly costs more than one built carefully the first time. We take the time to get the underlying analysis right before anything else, because compounding errors in deferred revenue are notoriously difficult to unwind.
Radical Transparency
We explain our reasoning at every step — not to impress, but because you need to defend these positions to your auditors, board, and investors independently of us. Opacity in advisory relationships creates dependency; we prefer to build your team's understanding alongside the deliverable.
Genuine Client Partnership
We do not parachute in with a template and leave. We work alongside your finance function, learning your contract structures and business model deeply enough to anticipate problems before they surface in a closing process or audit inquiry.
Regulatory Seriousness
Standards change. Interpretations evolve. We track developments from the AcSB, IASB, and relevant CPA Canada guidance continuously, so that the frameworks we build for you remain current and defensible as the regulatory environment shifts around them.
The People Behind Your Revenue Recognition Plans
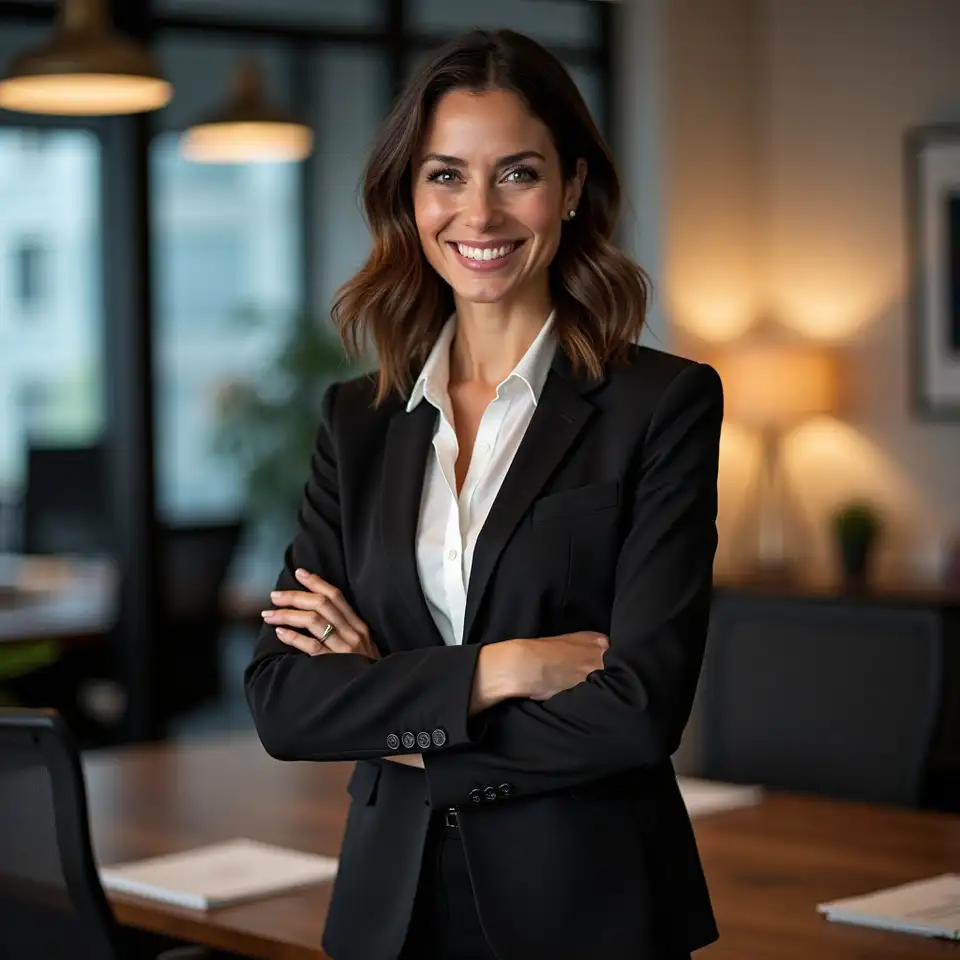
Margaret Osei-Bonsu, CPA, CA
Lead Revenue Recognition Advisor
Toronto, Ontario, Canada
«I spent a decade in public practice watching the same deferred revenue mistakes repeat across industries — not because the finance teams were careless, but because nobody had given them a clear planning structure to work from. That observation is what led me to build this practice around a single, solvable problem. When a client tells me their year-end close used to take three weeks of manual schedule reconciliation and now takes three days, that is the outcome I come to work for. The details matter enormously in this work, and I find genuine satisfaction in getting them right.»
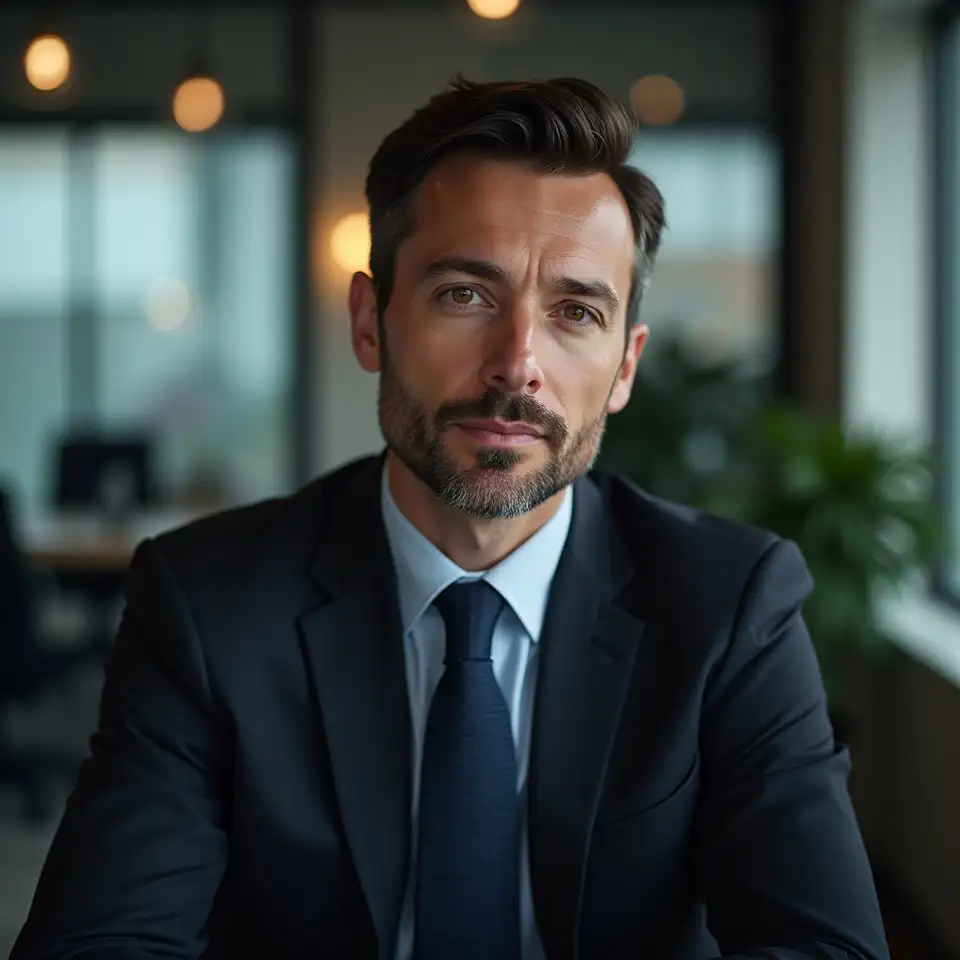
Daniel Ferreira, CPA, CGA
Senior Planning Specialist, Multi-Year Contracts
Vancouver, British Columbia, Canada
«Before joining this team, I spent years in industry finance roles at companies with large subscription and services portfolios. I lived through the pain of contract modifications that nobody had planned for, variable consideration estimates that auditors challenged, and disclosure notes written the night before filing. I brought all of that operational experience into our advisory work here. My goal with every client is to make sure their finance team could walk into an audit tomorrow and explain every line of their deferred revenue schedule without hesitation or improvisation.»
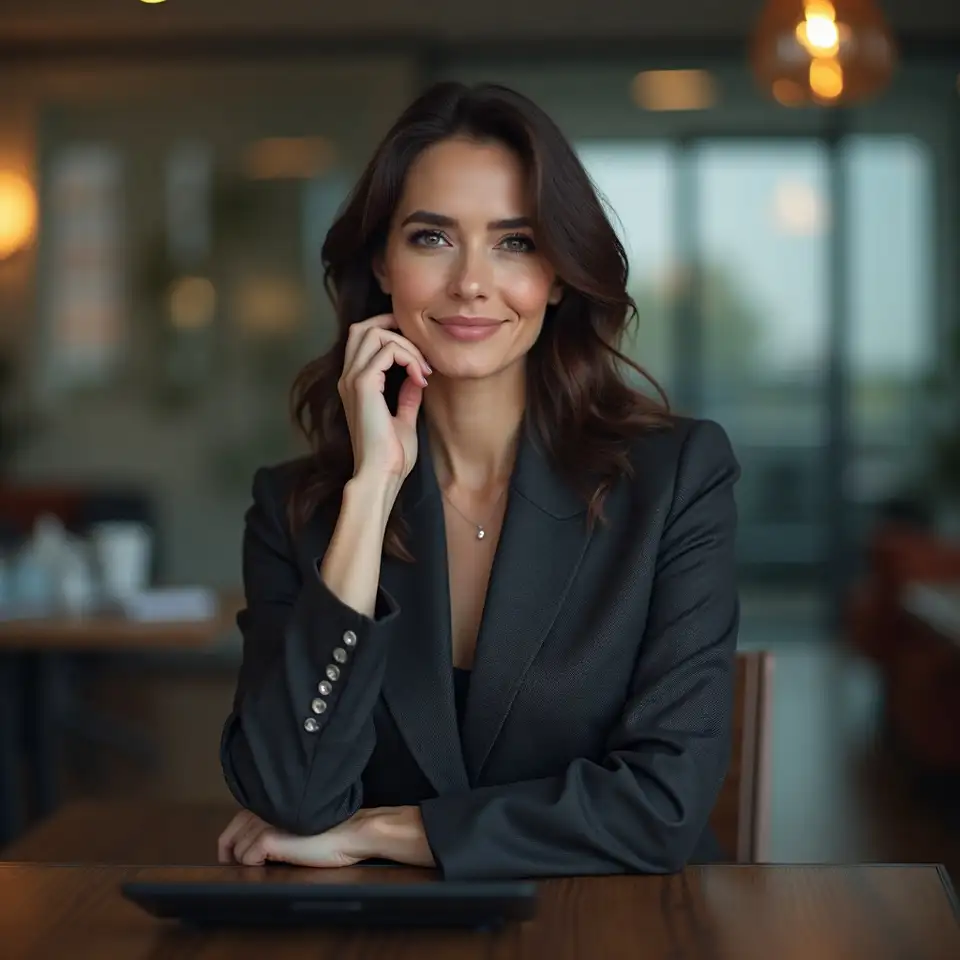
Priya Nair, CPA, CA, IFRS Specialist
Technical Standards and Disclosure Lead
Montreal, Quebec, Canada
«Revenue recognition standards are, at their core, a language — and like any language, the gap between technically correct and genuinely clear is enormous. My role is to help clients not just comply with IFRS 15 and ASPE Section 3400, but to communicate their revenue story in a way that earns the trust of readers who know what they are looking for. I pay particular attention to disclosure quality and the presentation of remaining performance obligations, because those notes reveal whether a company truly understands its own revenue model — or is simply filling in a template.»
Recognition and Credentials
Category
Award
Issuing Body
Year
Category:
CPA Fellow
Award:
Designated fellowship for sustained professional excellence
Issuing Body:
CPA Canada
Year:
2022
Category:
IFRS Advisory Panel
Award:
Appointed member, revenue recognition working group
Issuing Body:
AcSB Canada
Year:
2021
Category:
Technical Excellence Award
Award:
Recognized for contribution to revenue accounting guidance
Issuing Body:
CPA Ontario
Year:
2023
Category:
IMA Membership
Award:
Active professional member in good standing
Issuing Body:
IMA Global
Year:
2019
Category:
Best Practices Publication
Award:
Contributed to deferred revenue planning standards paper
Issuing Body:
CICA Research
Year:
2024
Start the Conversation
Your Deferred Revenue Deserves a Real Plan
There is a particular kind of stress that comes from closing the books when your deferred revenue schedules were built on assumptions nobody documented and methods nobody can quite explain to the auditor. We have seen it, and we know exactly how to unwind it. Whether you are building your first structured recognition framework or untangling a years-long backlog of ad hoc entries, our team is ready to work through it alongside you — methodically, transparently, and without judgment about how you got here. The next step is simply a conversation.
Clarity starts with one call
IFRS 15 Ready
Every recognition schedule we produce is structured to meet current
IFRS 15 and ASPE Section 3400 requirements, so your team walks into
audit conversations with documentation that holds up under scrutiny
without last-minute revision or explanation.
3-Step Process
Our internal planning methodology moves through three deliberate
phases — diagnostic review of your existing contracts, schedule
construction aligned to delivery patterns, and disclosure
preparation — giving your team a clear map of what happens and when
throughout the engagement.
Multi-Industry
We have worked with businesses across SaaS, professional services,
construction, and media — each with its own revenue timing
complexity — building planning frameworks that reflect the actual
economics of each model rather than applying a one-size template
across very different businesses.